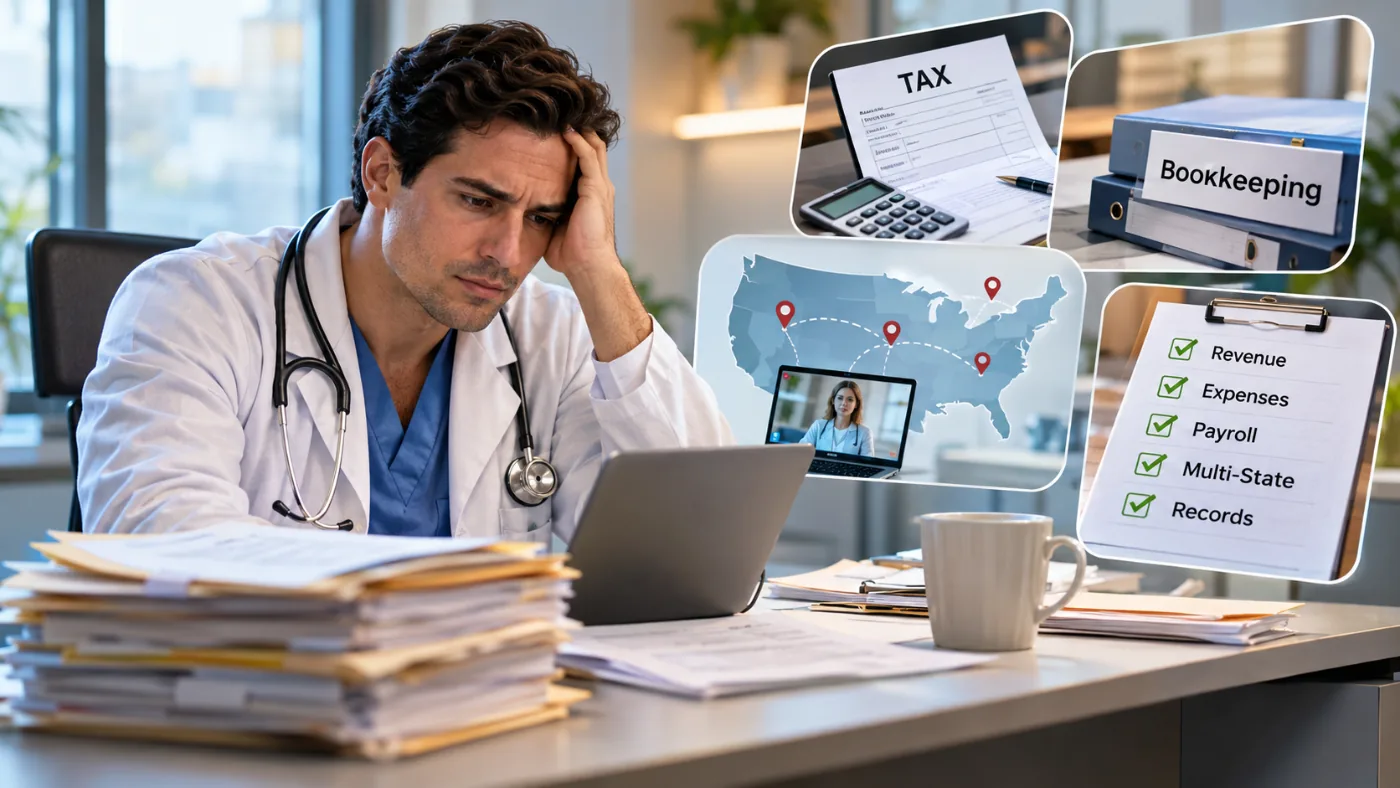
I have seen many doctors struggle with bookkeeping and tax filing. Interestingly, the problem is not always a lack of revenue or the complexity of their medical practice. More often, it is the difficulty of maintaining the right financial records throughout the year.
A doctor may have a billing team, an office manager, a payroll provider, and an accounting software subscription. Yet, when tax season arrives, the accountant is still chasing bank statements, insurance payment reports, equipment invoices, payroll records, and details of expenses paid personally by the physician.
Why does this happen?
A medical practice is not an ordinary service business. It has multiple sources of revenue, different payment arrangements, specialised expenses, and, in many cases, complex payroll and ownership structures.
The situation becomes even more complicated when the practice operates in multiple states or provides telehealth services across state lines.
Let's understand the problem through the example of a physician-owned S corporation.
1. Medical Practice Revenue Is Not as Simple as It Looks
In an ordinary business, revenue is generally easier to trace. A company provides a service, raises an invoice, receives payment, and records the transaction.
Medical practices work differently.
A patient visits the doctor. The practice records the service and submits a claim to the insurance company. The insurance company processes the claim, applies its contractual terms, and eventually sends a payment.
The amount billed is not necessarily the amount collected.
For example: A medical practice bills $300 for a consultation. The insurance company allows $180 under its contract. It pays $140, while the remaining $40 is assigned to the patient's responsibility.
The accounting records need to explain the entire transaction. The practice must be able to identify the amount billed, the contractual adjustment, the insurance payment, and the outstanding patient balance.
Now imagine hundreds of such transactions every month, involving different insurance companies, patients, providers, and locations.
This creates a significant bookkeeping challenge.
What records should a doctor maintain?
| Record | Why it matters |
|---|---|
| Patient service and charge summaries | Support the services billed during the period |
| Insurance claim submission reports | Identify claims submitted to different payers |
| Explanation of Benefits (EOB) | Show how an insurer processed a claim |
| Electronic Remittance Advice (ERA) | Explain insurance payments and adjustments |
| Insurance deposit reports | Help match payments with bank deposits |
| Patient payment receipts | Support copayments, deductibles, coinsurance, and other collections |
| Denied and rejected claim reports | Identify claims that remain unresolved |
| Contractual adjustment reports | Explain differences between billed and allowed amounts |
| Refund and recoupment reports | Support repayments and reversals |
| Accounts receivable ageing | Show outstanding insurance and patient balances |
One important point: the total value of claims submitted should not automatically be treated as the revenue figure for tax purposes. The accounting method and the nature of the contractual adjustments matter.
The accountant needs a reconciliation between the billing system, insurance reports, patient collections, bank deposits, and the accounting records. A bank statement alone cannot provide this information.
2. Doctors Often Have Expenses That Need More Detailed Documentation
A doctor may incur expenses that are quite different from those of a typical consulting or professional services business.
Some expenses are recurring. Others involve expensive medical equipment, professional registrations, insurance policies, and continuing education.
The challenge is not merely recording the payment. The practice needs to maintain evidence of the expense, its business purpose, the date, and, where relevant, the asset or location to which it relates.
Here are examples of records that should be maintained:-
| Expense category | Records to maintain |
|---|---|
| Medical supplies | Vendor invoices, receipts, and payment confirmations |
| Medical equipment | Purchase invoices, financing agreements, installation records, and placed-in-service dates |
| Malpractice insurance | Policy documents, premium invoices, and payment confirmations |
| Professional licensing | State medical board fee receipts and renewal records |
| Continuing Medical Education (CME) | Registration invoices, payment receipts, and course details |
| Medical software | Subscription invoices and service agreements |
| Electronic Medical Records (EMR) | Software invoices and implementation costs |
| Clinic rent | Lease agreements, rent invoices, and payment records |
| Laboratory and diagnostic services | Vendor invoices and service agreements |
| Professional fees | Legal, accounting, consulting, and billing service invoices |
| Employee expenses | Reimbursement claims, receipts, and approval records |
| Business travel | Dates, destinations, business purpose, mileage logs, and receipts |
3. Personal and Business Expenses Often Get Mixed Up
A physician may pay for a professional registration using a personal credit card. A medical conference may be booked through a personal account. The doctor may pay for a business subscription or purchase medical supplies personally.
The accounting team then needs to determine whether the payment was a business expense, a shareholder loan, a capital contribution, or a reimbursement.
These transactions should not be left as unexplained transfers between the physician and the corporation.
For an S corporation, this distinction becomes particularly important.
If the corporation reimburses an employee for business expenses under an accountable plan, the IRS requires a business connection, adequate substantiation within a reasonable period, and the return of excess reimbursement within a reasonable period.
For example, a doctor travelling to another clinic for business purposes should maintain the travel dates, destination, business purpose, expenses, and supporting receipts.
4. S Corporation Accounting Creates an Additional Layer of Complexity
Let's assume the physician operates through an S corporation.
The doctor is both the owner and an employee of the corporation. The corporation files Form 1120-S, and the shareholder receives Schedule K-1.
This structure requires the accounting records to distinguish between different types of transactions:
Physician salary: W-2 compensation for services performed. The S corporation must pay reasonable compensation to a shareholder-employee who provides services.
Shareholder distributions: Payments made to the doctor as an owner, not payroll expenses.
Shareholder loans and capital contributions: Money the doctor lends to or invests in the corporation. These must be recorded separately, along with any loan repayments.
5. Operating in Multiple States Makes Tax Records More Important
Consider a physician-owned S corporation with clinics in State A and State B, plus telehealth services for patients in other states.
The physician must generally be licensed or otherwise authorised to practise where the patient is located. However, medical licensing and tax obligations are separate matters.
Depending on the practice's activities, different states may require business registration, tax filings, or payroll reporting. The locations of clinics, employees, physicians, and patients may all be relevant.
What records should a multi-state medical practice maintain?
| Record | Why it matters |
|---|---|
| Physician licences and authorisations | Identify states where services may be provided |
| Clinic addresses and operating dates | Document physical business locations |
| Revenue reports by clinic and state | Support financial and state tax reporting |
| Service location reports | Identify where services were performed |
| Telehealth service summaries | Record provider and patient locations |
| Employee work-location records | Support state payroll analysis |
| State payroll withholding reports | Support payroll tax filings |
| State business registrations | Document entity registrations |
| State tax returns and payment confirmations | Maintain filing history |
| State-specific K-1 or allocation schedules, where applicable | Support shareholder reporting of state-source income |
6. Payroll Records Are More Than Just Salary Payments
Medical practices often employ physicians, nurses, medical assistants, receptionists, billing specialists, and administrative staff.
Payroll records need to support gross wages, deductions, employer payroll taxes, benefits, tax deposits, and year-end reporting. Where employees work in multiple states, their work locations and relevant state payroll information should also be documented.
The practice should maintain:
- Employee information and employment dates.
- Forms W-4 and payroll setup records.
- 1. Payroll registers and pay statements.
- Forms W-2 and W-3.
- Quarterly Forms 941 and annual Form 940, where applicable.
- Federal and state payroll tax payment confirmations.
- State withholding and unemployment filings, where applicable.
- Employee benefit and reimbursement records.
- Records supporting shareholder-employee compensation.
The IRS requires employers to retain employment tax records for at least four years after filing the relevant fourth-quarter return for the year.
7. The Records Needed for the Tax Return Should Be Collected Throughout the Year
Many doctors treat tax preparation as an annual exercise.
The accountant receives bank statements, expense summaries, payroll reports, and a list of equipment purchases. The team then starts requesting missing documents. This approach creates unnecessary work.
For an S corporation, the year-end tax package should summarise records already maintained throughout the year, not reconstruct the business from scratch.
Here is a practical annual record checklist for a physician-owned S corporation.
| Area | Records to provide or maintain for tax preparation |
|---|---|
| Corporate information | EIN, incorporation documents, ownership details, and prior-year tax return |
| Revenue | Billing summaries, insurance remittance reports, patient collections, refunds, and Forms 1099 received |
| Bank and credit cards | Year-end statements and completed reconciliations |
| Accounts receivable | Year-end ageing and relevant claim adjustment reports |
| Accounts payable | Outstanding vendor bills and year-end balances |
| Operating expenses | Invoices, receipts, statements, and payment records |
| Medical equipment | Purchase invoices, financing details, placed-in-service dates, and disposal records |
| Vehicle and travel | Mileage logs, travel records, business purpose, and receipts |
| Payroll | Payroll registers, W-2s, W-3, Forms 941 and 940, and tax deposit records |
| Shareholder compensation | W-2, payroll details, and health insurance reporting |
| Shareholder transactions | Distribution records, capital contributions, loan agreements, and repayments |
| Employee and contractor payments | W-9 information, payment records, and applicable Forms 1099 |
| Retirement and benefits | Plan statements, contribution records, and benefit invoices |
| Multi-state activity | State revenue schedules, employee work locations, registrations, and prior state filings |
| Tax payments | Federal and state estimated tax payments, payroll tax deposits, and notices |
8. There Is Also a Privacy Consideration
Medical billing records can contain protected health information (PHI).
When sharing records with bookkeepers, accountants, or tax preparers, practices should limit access to the information needed for financial reporting and use secure systems. Where a service provider acts as a HIPAA business associate, applicable privacy and contractual requirements also need to be addressed.
I believe the biggest mistake a medical practice can make is to view bookkeeping as a year-end activity. By the time the tax return is due, the difficult work should already have been completed.
Insurance collections should be reconciled. Expenses should have supporting documents. Equipment purchases should be properly recorded. Shareholder transactions should be identifiable. Payroll should agree with the tax filings. Multi-state activity should be supported by reliable records.
The tax preparer should not have to guess what a bank transfer represents or reconstruct a year's worth of insurance adjustments.
For a physician-owned S corporation, bookkeeping is not just about entering transactions into accounting software. It is about maintaining reliable financial records that support federal and state tax reporting.
A doctor should be able to focus on treating patients without having to become a full-time accountant as well.
At APG, we help healthcare practices and professional service businesses build organised bookkeeping processes, maintain reliable financial records, and prepare for their reporting and tax compliance requirements.
Disclaimer: This article is for general educational purposes only. It does not constitute individualised accounting, tax, or legal advice. Tax treatment, record retention, professional licensing, and state filing obligations depend on the facts of each business and applicable federal and state rules. Consult qualified professionals for requirements specific to your circumstances.
About APG
At APG, we believe incorporation is the first chapter of a business — not the whole story. We help founders navigate company registration, accounting, taxation and ongoing financial compliance, so they can focus on building businesses with confidence.
Ready to start your journey? Book a free consultation with APG and let's build your business on a strong financial foundation.
Book a free consultation →